
The growing role of listed bonds in Malta’s capital markets
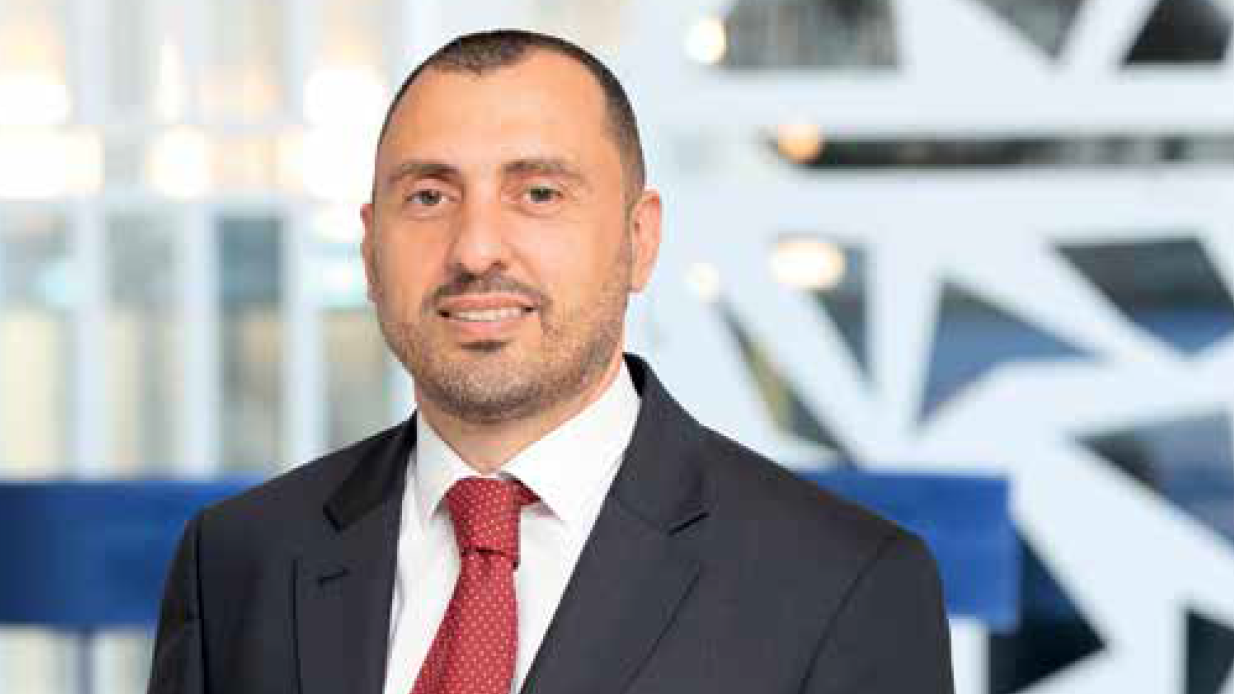
In recent years, Malta’s capital markets have undergone a noticeable shift in how local corporates approach financing. Bank lending remains a central pillar, but listed debt instruments – primarily bonds – are increasingly being used alongside traditional bank facilities rather than in place of them. As Patrick Mangion, Head of Capital Markets at Calamatta Cuschieri Moneybase (above photo: Darrin Zammit Lupi), notes, what was once seen as a relatively novel route to funding is now moving firmly into the mainstream.
From bank-led borrowing to listed debt
Local corporates have traditionally relied heavily on bank financing. That reliance has not disappeared, but it is now being complemented by listed bonds as companies look to diversify their funding sources. The market has matured, and businesses are more open to using public listings to support their growth and investment plans.
Rather than viewing listed bonds as competitors to bank lending, Mr Mangion stresses that the two forms of finance work best together. Both are sources of capital, but they operate very differently, and can be combined to create a more resilient and flexible funding structure.
How listed bonds differ from bank loans
Bank loans are typically structured as amortising facilities, where the borrowing company repays capital gradually over the term of the facility, alongside interest. Bonds, by contrast, tend to be repaid via a single ‘bullet’ payment at maturity, with interest paid regularly over the life of the bond.
There are further differences. Bank lending often carries a variable interest rate, whereas local bonds commonly offer a fixed rate. This allows an issuer to lock in its finance cost over the bond term and makes cashflow forecasting more straightforward. A bond is also a tradeable instrument, giving investors the option to exit before maturity – something that is generally not available with a standard loan.
Building a hybrid financing mix
Many companies are now recognising that the most effective financing model is a hybrid one that matches repayment structures to their cashflow profile. A clear example is a capital-intensive project with a long gestation period, such as a major property development or infrastructure initiative.
In such cases, the project may not generate returns immediately. Having to start repaying capital from day one under a bank facility can put pressure on cashflow. A bond with a bullet repayment profile can offer breathing space during the early years of the investment. This is one reason why Calamatta Cuschieri Moneybase often works alongside banks to deliver solutions that combine flexibility with financial sustainability.
Designing more flexible bond structures
Issuers also have a range of structuring tools at their disposal to enhance the flexibility of a bond. One increasingly common feature is a call option, which gives the issuer the right – but not the obligation – to redeem the bond before its final maturity date.
Another route is to obtain regulatory approval for a base programme, allowing the issuer to raise funds over a 12-month period instead of within a single offer window. Issuers can also divide the total amount they wish to raise into multiple tranches, each with different characteristics, to better match investor demand and funding needs.
Life as a listed corporate: obligations and benefits
A frequently asked question from prospective issuers concerns what changes are necessary once a company becomes a publicly listed entity. Listing brings increased responsibilities, including greater transparency, stronger reporting obligations and adherence to higher standards of corporate governance.
Many companies already have robust systems in place before they list, but the process of becoming a listed entity often acts as a catalyst for further improvement. According to Mr Mangion, it is not unusual for companies to return months after their listing to describe both the tangible and intangible benefits they have experienced as a result.
Planning ahead: preparation, cost and time to market
For businesses considering a listing, Mr Mangion’s advice is clear: seek guidance early, surround yourself with experienced advisers and avoid rushed decisions. Some of the most successful listings handled by Calamatta Cuschieri Moneybase began with conversations years before any transaction.
In one case, a client approached in 2019 and, after joint assessment, decided the timing was not yet right. When a new investment opportunity emerged later, the groundwork already done proved extremely valuable.
At Calamatta Cuschieri Moneybase, significant time is invested upfront – sometimes over several months and at no cost – to ensure the company is well prepared. The overarching aim is to deliver a strong, sustainable listing that serves the interests of all stakeholders.
Costs vary with the size and complexity of the issue, but for smaller transactions a broad indication is around 2-3% of the total offering size. On larger issues, costs tend to fall in relative terms due to economies of scale. Timelines depend heavily on how ready the company is. As a general guide, the period from first meeting to funds in hand is typically around four to six months.
Rising interest from professionals
Listing is no longer seen as a niche option. Calamatta Cuschieri Moneybase has noted growing interest from law and accountancy firms, which increasingly want to understand capital market solutions in more depth. Having a strong bond team – including professionals with accounting and legal expertise – is regarded as essential.
Even for companies with no immediate plan to list, it can be prudent to stay informed. In a rapidly changing business environment, opportunities can arise unexpectedly. Building knowledge in advance enables companies and their advisers to respond confidently when the right moment presents itself. The likelihood that a client or stakeholder will ask about listing options is higher than ever, making preparation important.
Taking the next step
For businesses exploring how listed debt instruments might fit into their wider financing strategy, now may be an opportune time to assess the options. Calamatta Cuschieri Moneybase positions its Capital Markets team to support issuers throughout the process, from initial discussions through to a successful listing, whether plans are near-term or still at the exploratory stage.
Calamatta Cuschieri Investment Services Ltd, at Level 0, Ewropa Business Centre, Dun Karm Street, Birkirkara BKR 9034, is licensed by MFSA to provide investment services. This article was first published in the Malta Stock Exchange Business Review 2025.